Closing Line Value (CLV) in Tennis: Why It Matters
 Available in US
Loading...
The only scoreboard that tells the truth
For years I judged my betting by the only number that felt real: my balance. Up this month, down that one, and no idea whether I was skilled or simply lucky. Then a sharper friend asked me a question that changed how I work. Not “did you win?” but “did you beat the close?” That single shift, from results to closing line value, is the difference between a punter who hopes and one who knows.
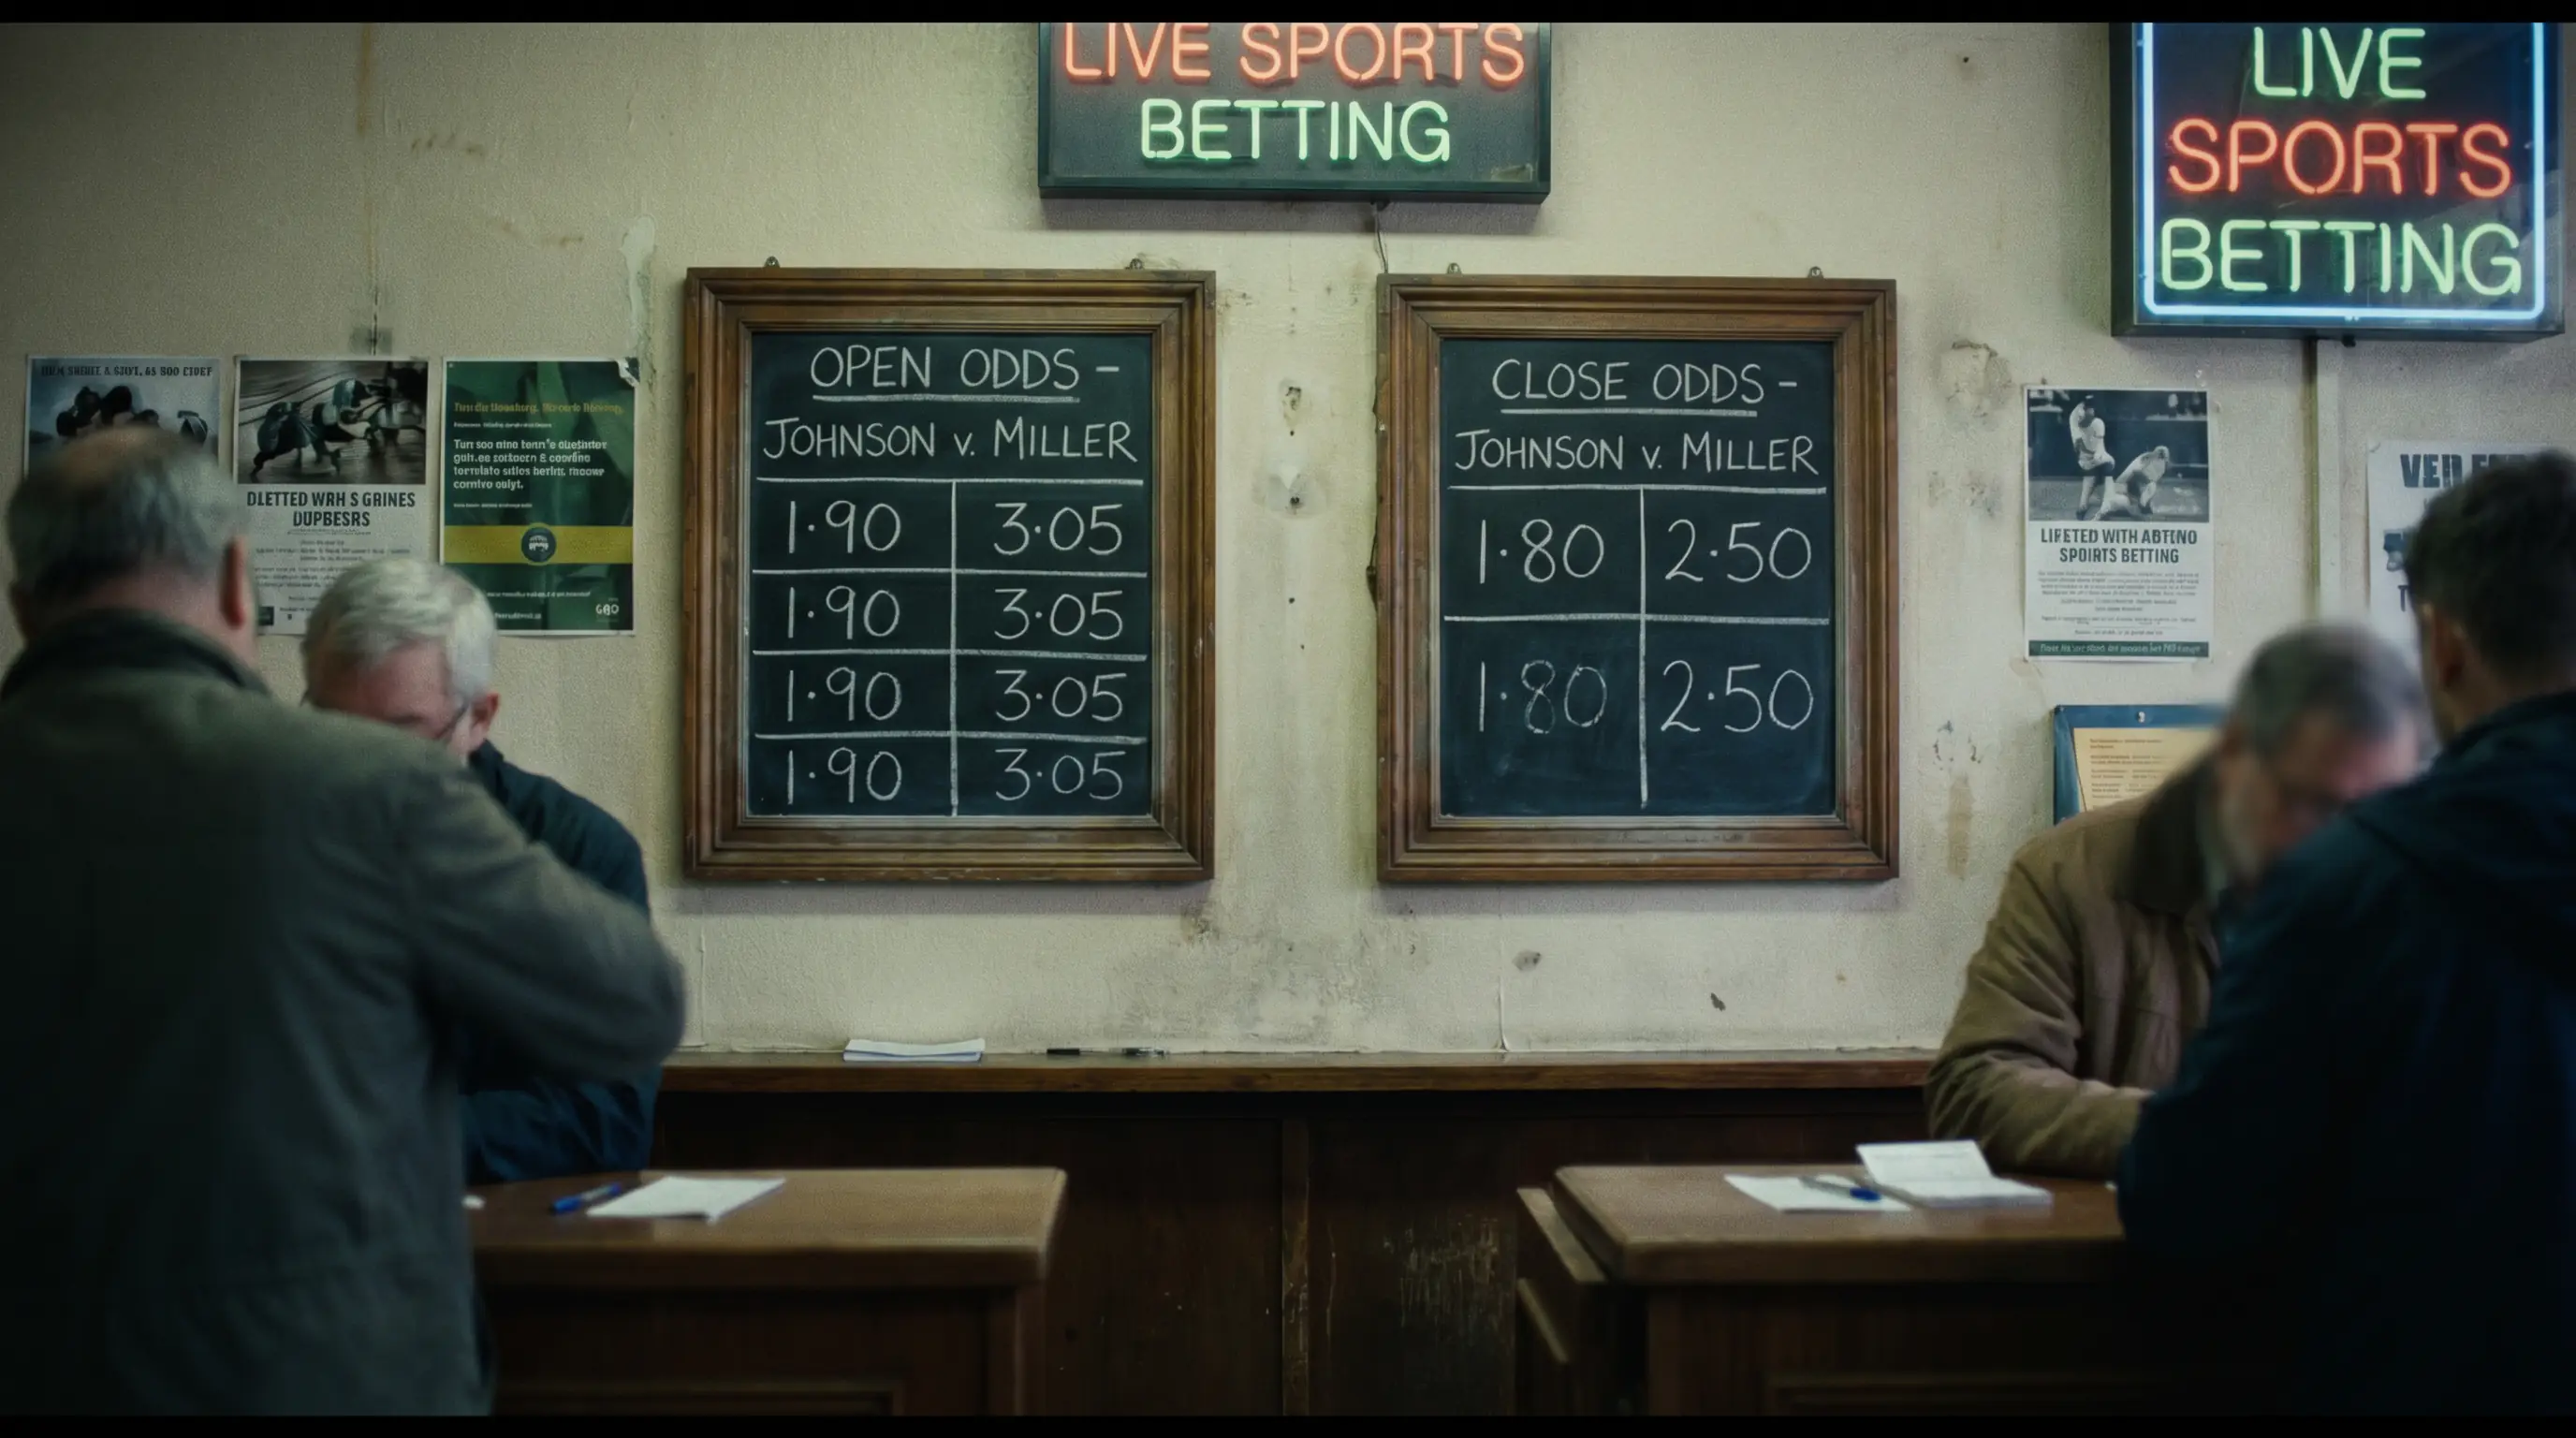
Closing line value, or CLV, measures whether the price you took was better than the price the market settled at just before the match began. Back a player at 2.20 and watch the price shorten to 1.90 by the off, and you have beaten the closing line. You bought at a better number than the market’s final, sharpest consensus. Do that consistently and you are almost certainly a winning bettor in the long run, regardless of how this week’s results happened to land.
The reason CLV carries so much weight is that the closing price is the market’s most accurate estimate of true probability. By the time a match starts, all the sharp money, all the team news, all the last-minute information has been absorbed into the number. If you routinely beat that number, you were ahead of the market, and being ahead of the market is the entire game.
What CLV actually measures
CLV is best understood as a proxy for being right before the crowd was. It does not tell you whether a single bet won. It tells you whether you bought value, and value is what compounds over hundreds of bets while individual results stay noisy.
Think of the closing line as the market’s final answer after a long exam. Early in the week the price is a rough guess, set by the bookmaker and lightly tested. As the match approaches, money pours in, the price sharpens, and by the off it reflects the collective intelligence of everyone who staked. When you take an early price that later shortens toward your side, the market has effectively agreed with you, validating your read after the fact. When the price drifts away from your selection, the market has disagreed, and over time disagreement is expensive.
This is why I trust CLV more than my balance over any short stretch. A run of beaten closing lines that happened to lose tells me my process is sound and variance is simply doing its thing. A run of wins that came from prices that drifted against me tells me I got lucky and should not get comfortable. The favourite-longshot bias, documented in tennis markets for the better part of two decades, also means the closing line on heavy favourites tends to be sharper than on longshots, so CLV is most reliable as a signal when you’re trading near the top of the market.
How to record CLV without a spreadsheet headache
The mechanics are simpler than people fear, and you do not need a trading desk to do this properly. For every bet, you log two numbers: the price you took and the price the same selection closed at. The difference, expressed as a percentage, is your CLV on that bet. Average it across a season and you have the single most honest read on your skill available to a recreational punter.
The one genuine complication is choosing your benchmark. On a traditional bookmaker, the closing price is the final odds offered before the market shut. On a betting exchange, where punters bet against each other, the natural benchmark is the last matched price before the off, which many sharp bettors treat as the truest closing line precisely because it strips out the bookmaker’s margin. Pick one benchmark and stay consistent; comparing an exchange close one week and a bookmaker close the next muddies the signal you’re trying to read.
Be ruthless about logging losers as well as winners, because that is where the discipline lives. The temptation is to record the bets that came in and quietly forget the ones that didn’t, but CLV only works as an honest mirror if every bet goes in the book. The deeper point is that CLV is the practical, day-to-day expression of value betting, and the full theory of how value is measured and priced sits in my colleague’s guide to finding value in tennis.
Why CLV beats this week’s results
Here is the uncomfortable maths that makes CLV indispensable. Tennis betting variance is brutal over small samples. You can make ten genuinely good bets and lose seven of them, then make ten poor bets and win eight, purely through the noise of a sport where the better player wins most matches but never all of them. Results over weeks or even months are a terrible guide to skill, and treating them as feedback will send you chasing the wrong lessons.
CLV cuts through that noise because it measures your decision at the moment you made it, not the random outcome that followed. A bet that beat the close was a good bet whether it won or lost, the same way a correctly priced insurance policy is sound whether or not the house burns down. Over a large enough sample, beating the close and making money converge, because the closing line is such an accurate estimate of true probability that consistently buying better than it is, mathematically, buying positive expectation.
So I’d offer the same advice my friend gave me. Stop asking whether you won this week. Start asking whether you beat the close. If you did, keep doing exactly what you’re doing and let variance sort itself out over the long run. If you didn’t, no winning streak will save you, because you’re buying worse than the market and the maths will catch up. CLV is the closest thing tennis betting has to a lie detector, and learning to read it is the moment you stop gambling and start investing in your own judgement.
Articles
Created by the "AceEdge" editorial team.
