The Kelly Criterion for Tennis Betting, Step by Step
 Available in US
Loading...
The formula that answers one question
Most staking advice I read is useless because it answers the wrong question. It tells you to bet small, or bet consistently, or never chase, which is fine as far as it goes. The Kelly criterion answers something far more precise and far more useful: given a known edge, exactly what fraction of your bankroll should you stake to grow it fastest without going broke? One question, one answer, and a surprising amount of danger hidden in the gap between the theory and tennis reality.
Kelly is a growth-optimal staking formula. Feed it your edge and the odds, and it returns the bankroll fraction that maximises your long-run growth rate. Stake more than Kelly says and you grow more slowly while risking ruin; stake less and you grow more slowly but more safely. It is mathematically elegant and genuinely powerful, which is exactly why it is so dangerous in the hands of a punter who overrates their own edge. The formula is only as honest as the numbers you put into it.
The Kelly formula itself
Let me write it plainly, because the algebra scares people off a tool they could actually use. For a simple win-or-lose bet, the Kelly fraction is your edge divided by the odds, or more precisely: f equals b times p minus q, all divided by b. Here b is the decimal odds minus one, the profit you make per unit staked if you win; p is your estimated probability of winning; and q is one minus p, your probability of losing.
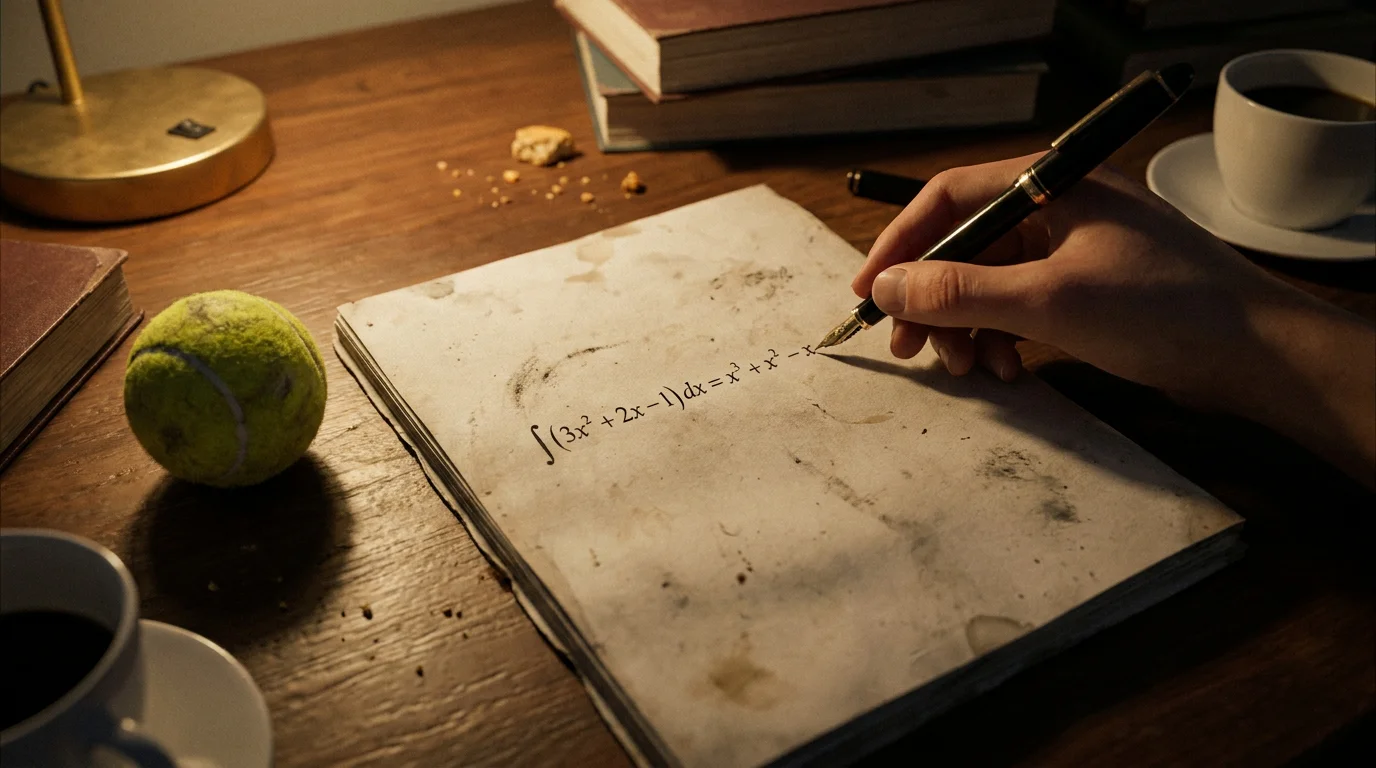
That looks abstract, so here is what it means in plain terms. The numerator, b times p minus q, is your expected profit per unit staked. If it’s positive, you have an edge and Kelly tells you to bet; if it’s zero or negative, Kelly tells you to stake nothing, which is itself valuable discipline. Dividing by b scales that edge against the odds, so longer-priced bets, where each win pays more, get a smaller fraction relative to their edge than you might expect.
The crucial input, and the one everything hinges on, is p, your estimate of the true probability. The odds you can read straight off the screen. Your edge you cannot, because it depends entirely on how accurately you’ve estimated p, and that is where tennis turns a beautiful formula into a minefield.
A worked tennis example
Numbers fix ideas, so here is a clean, brand-free example. You’re looking at a match where a player is available at decimal odds of 2.50. You’ve done your work on serve, surface and form, and you estimate this player’s true probability of winning at 45%, which would make the fair price about 2.22. The market is offering 2.50, so you believe you have value.
Plug it in. The decimal odds of 2.50 give b equals 1.50. Your p is 0.45 and your q is 0.55. The numerator is 1.50 times 0.45 minus 0.55, which is 0.675 minus 0.55, equals 0.125. Divide by b, 0.125 over 1.50, and you get a Kelly fraction of about 0.083, or roughly 8.3% of your bankroll. So full Kelly says stake more than eight pence in every pound you own on a single tennis match.
Read that figure again, because it should worry you. Eight percent of your entire bankroll on one match, on the strength of an edge you estimated by eye, is an enormous bet. If your estimate of 45% was even slightly optimistic, that 8.3% stake is no longer growth-optimal, it’s reckless. This is the moment most punters realise full Kelly is a theoretical ceiling, not a practical instruction, and why the framework behind estimating that edge in the first place, which I lay out alongside the broader staking models in my guide to tennis bankroll management and staking, matters more than the formula itself.
Why your edge estimate breaks Kelly
Here is the cruel asymmetry at the heart of using Kelly in tennis. The formula assumes you know your true win probability. You don’t. You estimate it, and your estimate carries error, and Kelly punishes overestimation far more harshly than it rewards accuracy. Overrate your edge and you don’t merely grow a little slower; you stake too much, ride larger swings, and march toward ruin while believing you’re being mathematically optimal.
Tennis makes this worse than most sports. The favourite-longshot bias means the market is already sharp on heavy favourites, so genuine edges there are thin and easily imagined. The variance of a sport where the better player wins most matches but loses plenty means your results give you slow, noisy feedback on whether your probability estimates were any good. By the time the numbers reveal you were overconfident, full Kelly has already amplified the damage across dozens of overstaked bets.
Surface adds another layer of estimation error. The same player can be a 70% proposition on a fast hard court, where servers held close to 87.8% of games at the quickest indoor events, and a coin flip on slow clay where breaks come freely. If your probability estimate doesn’t adjust for surface, your edge calculation is built on sand, and Kelly will faithfully scale up a stake based on a number that was wrong before you ever did the algebra.
The practical defence, used by essentially every serious bettor I know, is fractional Kelly. Instead of staking the full fraction, you stake a half, a quarter or even less of it. In the example above, half Kelly turns that alarming 8.3% into a more digestible 4.2%, and quarter Kelly into about 2%. You give up a little theoretical growth in exchange for a dramatic reduction in the risk that a string of overestimated edges wipes you out. Given that your p is always an estimate and estimates are always wrong to some degree, fractional Kelly isn’t timidity, it’s the only sane way to use a formula that assumes a certainty you’ll never actually have. Use Kelly to size your conviction, then halve it because you’re human, and you’ll have taken the best of the maths while protecting yourself from its single fatal assumption.
Articles
Published by the AceEdge team.
